• Skip to main content
  • Skip to header right navigation
  • Skip to site footer
  • Blog
  • Free Resources
RevistaMed

RevistaMed

  • About
    • Meet Revista
    • Advisory Board
    • Partners
    • Press
    • Rising Leaders Council
    • Sponsorship
    • Contact Us
  • Events
    • Annual Events
    • Subscriber Webinar
  • Why Subscribe?
    • Schedule a Demo
    • Featured Products
    • Business Development
    • Underwriting & Due Diligence
    • Asset Management
    • Capital Markets
    • Site Selection & Development
    • Leasing
  • Subscriber Login
Home / Real Estate Financing/Capital Markets / Inpatient Rehabilitation Hospitals: A National Perspective on a Resilient Healthcare Real Estate Asset Class

Inpatient Rehabilitation Hospitals: A National Perspective on a Resilient Healthcare Real Estate Asset Class

January 28, 2026 by CJ Kodani Topics: Construction/Development, Real Estate Financing/Capital Markets, Transactions

INPATIENT REHABILITATION HOSPITAL OVERVIEW

An inpatient rehabilitation hospital is a state-licensed acute-care facility dedicated to providing intensive rehabilitative services to patients recovering from major medical events such as strokes, orthopedic surgeries, neurological injuries, and complex illnesses. IRFs operate within the post-acute care continuum and serve patients who require daily physician oversight and multidisciplinary therapy following discharge from a short-term acute-care hospital. Compared to other post-acute settings, IRFs benefit from a relatively structured and predictable Medicare reimbursement framework, contributing to operational and revenue stability.¹
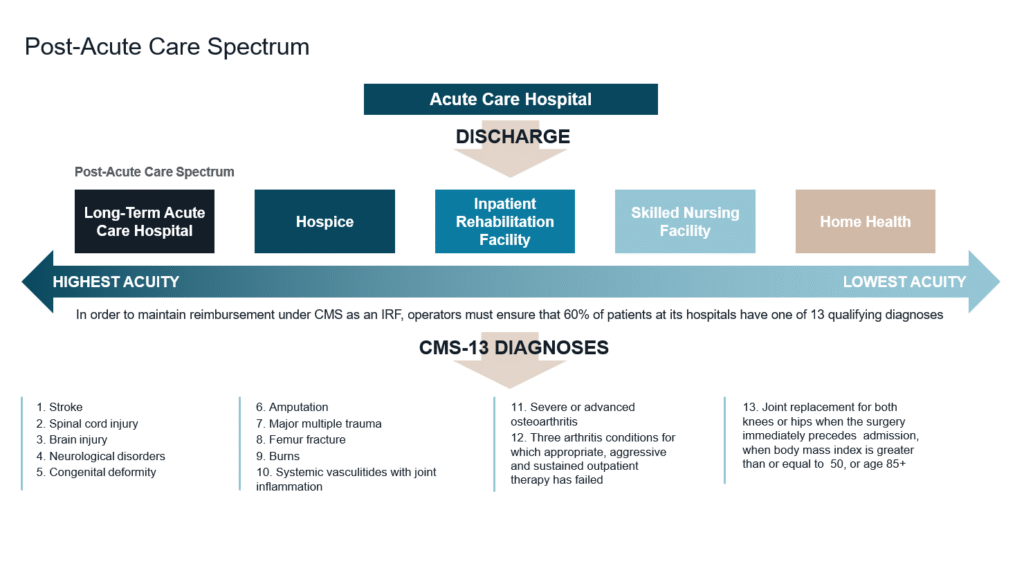
As investors seek durable yield in a decreasing interest rate environment, IRFs continue to attract interest from both domestic and foreign institutional capital—trends that show little sign of slowing. As capital markets normalize, IRFs have emerged as a rapidly expanding segment within U.S. healthcare real estate, benefiting from hospital-level care, long-term absolute net lease structures, durable demand fundamentals, and a development environment with high barriers to entry.

SUPPLY AND CONSTRUCTION TRENDS

As the ongoing shift from hospital-in-hospital rehabilitation units to freestanding inpatient rehabilitation facilities continues, the number of operating IRFs nationwide has increased from approximately 306 facilities in 2014 to more than 510 as of mid-2025—representing growth of roughly 67%.² This expansion has been driven primarily by freestanding IRFs developed in partnership with national operators, reflecting both rising demand for rehabilitation services and increasing institutional acceptance of the asset class.

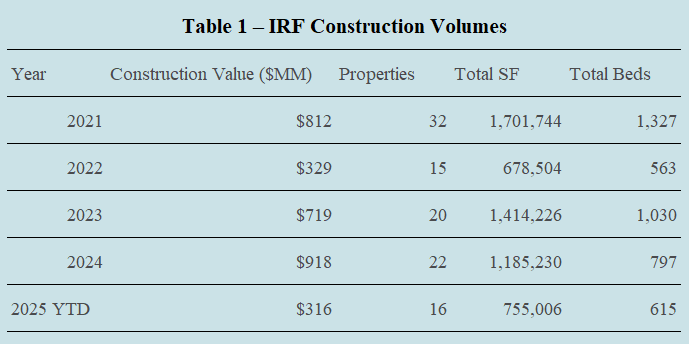
Consistent with this long-term growth trend, construction activity within the IRF sector has accelerated in 2025. According to RevistaMed, development volumes over the 12-month period leading into mid-2025 reached approximately 1.9 million square feet, surpassing the trailing twelve-month average of roughly 1.85 million square feet recorded from 2021 through 2024.² Table 1 outlines IRF construction activity from 2021 through year-to-date 2025.

Development volumes declined sharply in 2022 as rising borrowing costs, initial sticker shock around construction pricing, and a temporary misalignment between development yields and exit cap rates caused many projects to pause. Activity, however, quickly recalibrated as developers, institutional investors, and post-acute care operators recognized the recession-resilient nature of the IRF asset class, its essential role within the healthcare delivery continuum, and adjusted underwriting assumptions and deal terms accordingly.

From 2021 through the first half of 2025, more than 105 new IRF developments were delivered nationwide, totaling approximately 4,332 beds across 5.73 million square feet of new construction.³
IRF PRICING TRENDS

Freestanding IRF pricing for core-plus transactions in the United States has improved materially, with cap rates compressing from the high-6% to low-7% range during 2022–2024 into the mid-6% range in 2025.⁴ This improvement has been driven by increased equity capital entering the sector, tightening lender spreads and benchmark indices, and a steadily improving healthcare reimbursement environment.

GP EQUITY INVESTMENT THRESHOLDS IN IRF TRANSACTIONS

Equity structuring dynamics for IRFs have evolved as capital has become more experienced and selective. General partner equity contribution requirements for IRF acquisitions and developments have generally remained lower than those observed in non-healthcare asset classes, reflecting IRFs’ long-term lease structures, institutional tenancy, and recession-resistant cash flows. In most IRF transactions, GP investment thresholds typically range around 5-10% of total equity, allowing experienced operators and developers to remain economically aligned while still preserving sufficient sponsor diversification for equity partners.4

While equity investors in other commercial real estate sectors have pushed GP contribution requirements materially higher in recent years, IRF-focused investors have largely maintained more moderate thresholds. This has increased competition among sponsors and placed greater emphasis on differentiated operating strategies, health system relationships, and demonstrated execution capabilities within the IRF space.4

DEBT FINANCING AND LEVERAGE TRENDS FOR IRFS

Debt capital availability for IRFs remains robust but more conservative than during the prior low-rate cycle. In 2020 and early 2021, lenders were willing to advance highly levered financing for single-tenant healthcare assets; however, current IRF transactions are typically structured with loan-to-cost or loan-to-value ratios in the 60% to 65% range, depending on post-acute care operator scale, health system joint venture partner credit, lease term economics, and underlying market fundamentals.⁴

The reduction in leverage has widened the capital stack and created opportunities for common equity, preferred equity, and mezzanine capital to participate in IRF acquisitions and developments. For well-capitalized investors, this shift has improved risk-adjusted return profiles while reinforcing disciplined underwriting across the sector.⁴

2026 AND BEYOND

Looking ahead, IRFs are positioned to remain a key component of the U.S. healthcare ecosystem as the IRF healthcare delivery model aligns the interests of post-acute care operators, patients, and governmental payors, creating a framework that supports quality outcomes, operational efficiency, and reimbursement sustainability. These attributes make IRFs an attractive asset class for institutional capital, a trend we expect to continue for the foreseeable future.

REFERENCES

¹ Centers for Medicare & Medicaid Services (CMS), Inpatient Rehabilitation Facility Overview.

2 RevistaMed, “Rehabilitation Hospital Construction Showing Signs of Rising in 2025.”

3 RevistaMed, Post-Acute and Rehabilitation Hospital Real Estate Data, 2021–YTD 2025.

⁴ Colliers US Healthcare Capital Markets Research.
CJ Kodani

Senior Vice President, Colliers, US Healthcare Capital Markets

Other Articles by CJ Kodani:

Previous Post:A Quick look at the 2026 MREIF Host Metro – Los Angeles
Next Post:Medical Office Rent Growth Normalizes Post Inflation

Sidebar

Topics

  • Construction/Development
  • Industry News
  • Leasing/Property Management
  • Mergers/Acquisitions
  • Policy/Legislation
  • Real Estate Financing/Capital Markets
  • Revista Best Practices
  • Revista News
  • Sponsor Spotlight
  • Transactions
  • Uncategorized

Archives

RSS feed: Recent Blog Posts Recent Blog Posts

  • Revista Updates the Size and Scope of the Medical Real Estate Sector September 29, 2026
    Revista has updated the size and scope of the Medical Real Estate Sector (MRE or HCRE).  The October 2026 update shows that the HCRE sector (all inpatient and outpatient real estate) contains roughly 3.6 million square feet (SF) and carries a valuation of $1.6 trillion (T).  The post Revista Updates the Size and Scope of […]
    Mike Hargrave
  • Which Markets are Investors Gaining Share of Outpatient Real Estate? August 28, 2026
    In the table below we compare these two numbers for each of the Top 50 markets and rank them by the largest shift towards investor-ownership relative to the markets size. Birmingham tops the list with a net . . . The post Which Markets are Investors Gaining Share of Outpatient Real Estate? appeared first on […]
    Stephen Lindsey
  • Developers and Providers Turn to Conversion Opportunities August 27, 2026
    While attractive, conversion potential has historically been limited because medical requirements differ significantly from those of traditional office or retail buildings. Specialized HVAC, infrastructure to support heavy medical equipment, significant … The post Developers and Providers Turn to Conversion Opportunities appeared first on RevistaMed.
    Hilda Martin
  • Large Hospital Pipeline, but Starts Trending Down July 31, 2026
    There are currently 74.2 million square feet of hospitals under construction across the US. That is down year-over-year, but still a very string pipeline when compared to the past decade. There is a total of 237 . . . The post Large Hospital Pipeline, but Starts Trending Down appeared first on RevistaMed.
    Stephen Lindsey

Other Free Resources

Industry Directory

Search for and/or list your medical real estate services in Revista’s medical real estate directory.

Reports & White Papers

Download free reports & white papers on medical real estate.

Add Lease/Sale Listing

Revista provides free lease/sale listings for healthcare real estate.

Archives

  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • January 2024
  • December 2023
  • November 2023
  • October 2023
  • September 2023
  • August 2023
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
  • February 2023
  • January 2023
  • December 2022
  • November 2022
  • October 2022
  • September 2022
  • August 2022
  • July 2022
  • June 2022
  • May 2022
  • April 2022
  • February 2022
  • January 2022
  • December 2021
  • November 2021
  • October 2021
  • September 2021
  • August 2021
  • July 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • December 2016
  • November 2016
  • October 2016
  • September 2016
  • August 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • December 2015
  • November 2015
  • October 2015
  • September 2015
  • August 2015
  • July 2015
  • June 2015
  • April 2015
  • March 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • July 2014
  • June 2014
  • May 2014
  • April 2014

Categories

  • Construction/Development
  • Industry News
  • Leasing/Property Management
  • Mergers/Acquisitions
  • Policy/Legislation
  • Real Estate Financing/Capital Markets
  • Revista Best Practices
  • Revista News
  • Sponsor Spotlight
  • Transactions
  • Uncategorized

Meta

  • Log in
  • Entries feed
  • Comments feed
  • WordPress.org

Ready to Schedule a Demo?

Get in Touch Now

  • Why Subscribe?
  • Events
  • The MOB Scene
  • Add A Directory Listing

  • Add Lease/Sale Listing
  • Contact Us
  • Sponsorship

  • About
  • Data Terms of Use
  • Sponsorship Terms
  • Press

SIGN UP FOR MOB SCENE NEWSLETTER

  • This field is for validation purposes and should be left unchanged.
  • Twitter
  • Facebook
  • LinkedIn